
In-Home Care for Seniors: Types, Costs, and How to Find Good Care (2026)
A practical guide to in-home care for seniors: the types, what it costs in 2026, whether Medicare or Medicaid pays, and how to find a caregiver you trust.
ElderHearth offers general information, not medical, legal, or financial advice. For your parent's specific needs, ask their doctor for a referral to a social worker or care manager.
When a parent needs more help than family can give, but a nursing home is not the answer, in-home care for seniors is usually the next step, and it is the option most older adults want. The trouble is that "home care" covers several very different things, the cost surprises most families, and it is hard to know how to find someone you can trust in your parent's home. This guide lays out the whole picture: the types, the 2026 costs, who pays, and how to hire well.
What is in-home care for seniors?
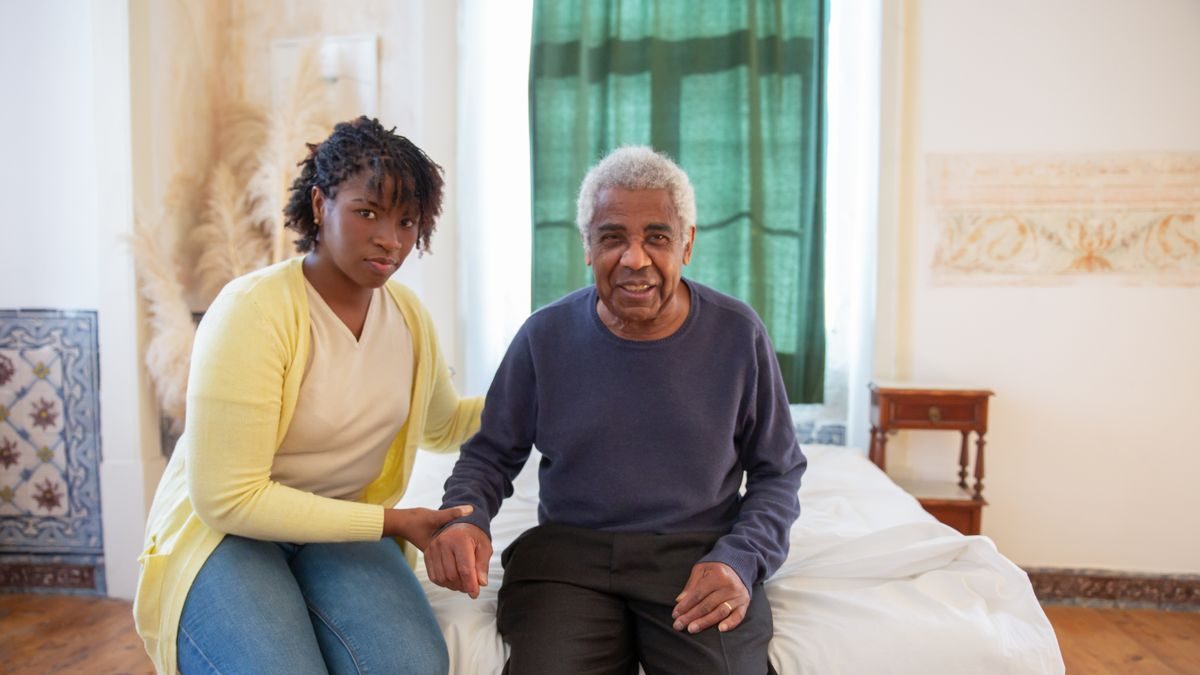
In-home care is help that comes to your parent's house so they can keep living there. It splits into two categories that families constantly mix up, and getting the difference straight is the single most useful thing you can do:
- Non-medical home care (also called personal care or custodial care) is help with daily life: bathing, dressing, meals, light housekeeping, medication reminders, and company. Most in-home care is this kind. Medicare does not pay for it.
- Medical home health care is skilled, clinical care ordered by a doctor: a nurse, or a physical, occupational, or speech therapist. Medicare can pay for this, in specific circumstances covered below.
Almost every confusion about cost and coverage traces back to this line. When people say "Medicare covers home care," they mean the medical kind, briefly, not the day-to-day help most parents actually need.
Home care vs home health: the types of in-home care
Within those two categories, you can hire:
- Companion care. Company, conversation, supervision, errands, and light help around the house. Best for a parent who is mostly independent but should not be alone all day.
- Personal care aide / home health aide. Hands-on help with bathing, dressing, toileting, and moving safely. This is the workhorse of in-home care.
- Skilled home health. A nurse or therapist for wound care, injections, monitoring, or rehab after a hospital stay. Doctor-ordered and time-limited.
- Live-in or 24-hour care. For a parent who cannot be safely alone at any hour. The most expensive option, and the point where families often start weighing other choices.
Care can be a few hours a week or around the clock, and many families start small and add hours as needs grow. And if a family member is the one providing that care, they may be able to get paid for it; see how to get paid to care for an elderly parent.
How much does in-home care cost in 2026?
In-home care is billed by the hour, and it adds up faster than most families expect. The most recent national Cost of Care Survey from Genworth and CareScout puts the median for a home health aide at roughly $30 to $35 an hour, with rates higher in expensive metro areas and lower in some rural ones. That works out to well over $5,000 a month for full-time weekday help, and considerably more for live-in or 24-hour care.
Two things move that number:
- How many hours. A few mornings a week is manageable; round-the-clock care can rival or exceed the cost of assisted living.
- Agency or independent. Hiring directly is usually cheaper per hour, but the agency price includes vetting, backup coverage, insurance, and payroll taxes you would otherwise handle yourself (more below).
Because the monthly total climbs so fast, plan the money before you plan the schedule. Our guide to how to pay for an aging parent's care walks through every funding source in one place.
Does Medicare or Medicaid pay for in-home care for seniors?
This is where the categories above decide everything:
- Medicare covers part-time or intermittent skilled home health (nursing and therapy, plus a home health aide only alongside that skilled care) for a parent who is homebound and under a doctor's plan of care. It does not cover ongoing non-medical personal care, 24-hour care, meals, or homemaker services on their own.
- Medicaid is the better source for long-term home care. Through Home and Community-Based Services (HCBS) waivers, state Medicaid programs pay for personal care at home for those who qualify, the same waivers behind our state assistance guides. Income and asset limits apply and vary by state.
- Long-term care insurance, if your parent has a policy, is designed for exactly this; see our guide to long-term care insurance.
- VA benefits, for eligible veterans, and out-of-pocket funds cover the rest.
The short version: for day-to-day help at home, do not count on Medicare. Look to Medicaid, insurance, VA, and private pay.
Agency or hiring a caregiver independently?
Once you know the type and the budget, this is the practical fork.
A home care agency costs more per hour but handles the hard parts: it screens and background-checks caregivers, covers shifts when someone is sick, carries liability insurance, and manages payroll and taxes. If a caregiver does not work out, the agency sends someone else.
Hiring independently (finding a caregiver yourself) costs less per hour and lets your parent keep the same person, but you become the employer: you vet them, arrange backup when they are unavailable, and handle taxes and liability. It can work beautifully with the right person and a solid backup plan, and it can leave you stranded when that person calls in sick.
Neither is wrong. Agencies suit families who want reliability and less to manage; independent hiring suits those with time to manage it and a trusted candidate.
How to find and vet a good caregiver
However you hire, the vetting is what protects your parent:
- Write down the actual needs first: which tasks, which hours, any medical or memory issues, so you can match the right skill level.
- Start with trusted sources: your parent's doctor or hospital discharge planner, the local Area Agency on Aging (reach it through the Eldercare Locator at 1-800-677-1116), and personal referrals.
- Interview for fit, not just credentials. Ask how they would handle a refusal to bathe, a fall, a bad day. Watch how they talk about older adults.
- Check references and run a background check (agencies do this; if you hire independently, do it yourself).
- Start with a trial and watch closely: is your parent comfortable, clean, fed, and calm? Trust your parent's reaction and your own gut.
If your parent resists the whole idea of a stranger in the house, that is common and worth handling gently; the same approach that works for a parent who refuses help applies here.
When in-home care isn't enough
In-home care stretches a long way, but not forever. When a parent needs supervision at every hour, wanders, or their needs outpace what hourly care can safely cover, it may be time to compare options. Our guides to the signs a parent can't live alone and aging in place versus assisted living can help you judge where that line is. And if arranging all of this is wearing you down, that exhaustion is real; see caregiver burnout and don't skip your own caregiver health checklist, because bringing in help is often what saves the caregiver too. For families caring from another town or state, in-home care is also your most reliable set of local eyes; our guide to long-distance caregiving covers how to build the rest of the team.
If the help is needed because a hospital stay is ending sooner than the family expected, that discharge date can be formally reviewed before anyone arranges anything, and our guide to the hospital discharge appeal sets out the deadline and who pays while the review runs.
Frequently Asked Questions
How much does in-home care cost? Most in-home care is billed hourly, with a national median around $30 to $35 an hour for a home health aide in the most recent Genworth and CareScout survey. Full-time weekday help runs well over $5,000 a month, and live-in care costs more. Rates vary widely by location.
Does Medicare pay for in-home care? Only for part-time or intermittent skilled care (nursing or therapy) for a homebound parent under a doctor's plan. Medicare does not cover ongoing non-medical personal care, 24-hour care, or homemaker services. Medicaid, long-term care insurance, and VA benefits are the sources for day-to-day home care.
What is the difference between home care and home health? Home care (non-medical) is help with daily life such as bathing, dressing, meals, and company. Home health (medical) is skilled, doctor-ordered care from a nurse or therapist. Medicare can cover home health in specific cases, but not ongoing non-medical home care.
How do I find a caregiver for an elderly parent? Start with your parent's doctor or hospital discharge planner, the Area Agency on Aging (Eldercare Locator, 1-800-677-1116), and referrals. Interview for fit, check references and backgrounds, and begin with a trial period while you watch how your parent responds.
Is it better to hire through an agency or independently? An agency costs more but handles vetting, backup coverage, insurance, and taxes. Hiring independently costs less and keeps the same caregiver, but you take on the employer role, including backup and taxes. The right choice depends on your budget and how much you want to manage.
A last word
In-home care for seniors is often the answer that keeps a parent where they want to be, at home, without asking the family to do everything alone. Get the two types straight, plan the cost before the schedule, look past Medicare to the sources that actually pay for daily help, and vet whoever comes into the house as if your parent's safety depends on it, because it does. Done well, it is one of the surest ways to keep a parent aging safely in place.
If you would like someone to read what you are dealing with, you are welcome to write to us.
Sources
- Medicare.gov, Home health services.
- Genworth and CareScout, Cost of Care Survey.
- Eldercare Locator, Area Agencies on Aging.
- National Institute on Aging, Aging in Place: Growing Older at Home.